
2025 Financial Planning Q&A
ADVICE December 27, 2025
ADVICE December 27, 2025
To balance out the mortgage and lending side of the 2025 conversation, I also sat down with Andrew Baker, Financial Advisor at Financial Haus, to talk about the bigger picture. We covered year-end planning, saving, investing, debt, and the habits that actually move the needle long term. Below is our full Q&A, shared exactly as discussed.
A: A year-end money audit. Look at your cash flow, update your net worth, confirm your savings rate, list your debts, and check your emergency fund. Most people avoid this because it feels overwhelming, but clarity is the fastest path to control.
A: Review retirement contributions, HSA funding, charitable giving, and opportunities for tax-loss harvesting. Small moves before 12/31 can meaningfully reduce taxable income.
A: Automate as much as possible: savings, investing, bill pay. When the essentials run on systems instead of willpower, building wealth becomes easier.
A: Their savings rate is the main indicator. Aiming for 15–25% of gross income across all accounts puts most people on track. Those pursuing early financial independence will usually need to save more.
A: Look at three areas: security, stability, and growth.
If someone has no emergency fund, savings comes first.
If they have high-interest debt above roughly 10–12%, pay that down.
If both are solid, invest for future goals. Your weakest area sets your priority.
A: Adjust intentionally, not emotionally. Rebalance once a year, confirm the investment mix matches your time horizon, and make sure risk is aligned with your actual goals, not the news cycle.
A: Ask two questions: Do I have 3–6 months of expenses saved? Will I need this money within the next 2–3 years?
If the answer is no and yes, keep cash.
If the answer is yes and no, investing typically makes more sense.
A: Any major change that affects someone’s income, expenses, or priorities: moving, marriage, divorce, new job, career transition, having a child, buying property, receiving an inheritance, or starting a business. Transitions are a natural time to adjust the plan.
A: Use a simple cash-flow structure instead of strict budgeting. Pay-yourself-first, 50/30/20, or weekly spending check-ins work well. Automation removes the need for constant discipline, and small weekly reviews prevent things from spiraling.
A: Avoiding finances out of fear, inconsistent habits, emotional spending, debt patterns, and confusion around investing. Once people have clarity, structure, and accountability, confidence usually replaces anxiety quickly.
A: Money grows when you give it direction.
Your habits matter more than your income.
To get in contact with Andrew
ANDREW BAKER
Financial Planner | Founder
California Insurance License #0I4437
1253 University Ave #1002
San Diego, CA 92103
Cell: +1 619 357 0402
Office: +1 619 641 3619
Stay up to date on the latest trends in real estate.

October 9, 2026
Real listings, price per square foot by neighborhood, and the tradeoffs buyers face this fall

October 9, 2026
What San Diego's airport soundproofing program covers, who qualifies, and what buyers and sellers should know

October 9, 2026
A local guide to Loma Portal, La Playa, Fleetridge, Sunset Cliffs and more, and who each one suits
October 4, 2026
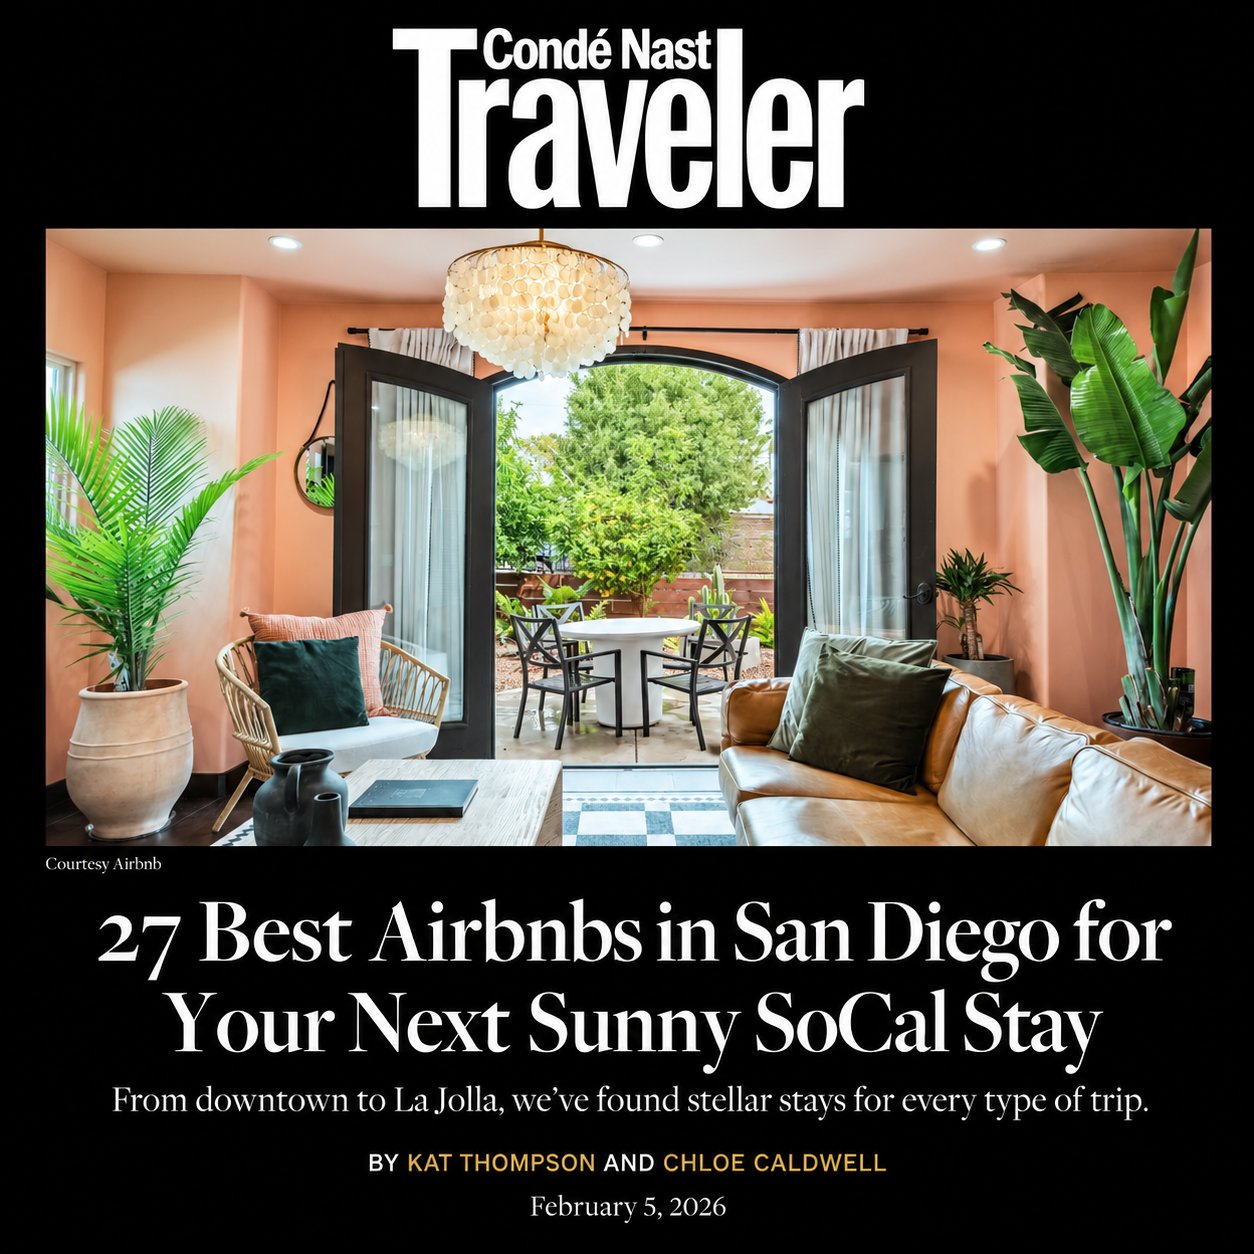
Our Mountain View retreat is featured in Condé Nast Traveler's guide to San Diego's best Airbnbs for the fourth year in a row

October 3, 2026
Neighborhoods, nightlife and what to expect, from a gay realtor who lives here

October 3, 2026
How a 2% seller credit can lower your monthly payment more than a price cut

October 3, 2026
How STR owners use cost segregation and 100% bonus depreciation to write off more in year one
September 30, 2026

September 16, 2026
Get assistance in determining current property value, crafting a competitive offer, writing and negotiating a contract, and much more. Contact Josh today.