
What Is an Impound Account and How Does It Work?
November 8, 2025
November 8, 2025
When buying a home, you’ll hear plenty of terms thrown around by lenders and agents — and one that often confuses buyers is the impound account (sometimes called an escrow account). While it might sound complicated, an impound account is actually designed to make your life easier.
An impound account is a special account your lender sets up to collect and hold money for your property taxes. Instead of paying this large bill once or twice a year, your lender divides the total amount into smaller monthly portions and adds them to your mortgage payment.
When your property taxes come due, your lender uses the funds in your impound account to pay them on your behalf. This ensures the bills are paid on time and you don’t get hit with any late fees or penalties.
Peace of mind – Your lender handles the payments, so you won’t have to remember tax deadlines.
Budgeting made simple – Spreading large annual or semi-annual costs over 12 months keeps your monthly expenses predictable.
Avoiding penalties – Since payments are automated, you won’t risk missing due dates.
Balance changes – If your property taxes go up or down, your lender will adjust your monthly payment after an annual review. You’ll receive an escrow analysis explaining any changes.
Initial deposit – When your account is set up at closing, your lender will require a starting balance to cover upcoming bills, which is often two to three months’ worth of payments.
Optional or required – Depending on your loan type and down payment amount, an impound account might be mandatory. For example, FHA and VA loans generally require them, while conventional loans may allow you to opt out if you have strong credit and put down at least 20%.
If you prefer simplicity and predictability, an impound account is a great option. But if you’re highly organized and like controlling your cash flow, you may prefer to handle your property tax payments on your own.
Either way, understanding how impound accounts work helps you make an informed decision — and keeps your homeownership journey smooth and stress-free.
Stay up to date on the latest trends in real estate.
October 17, 2026
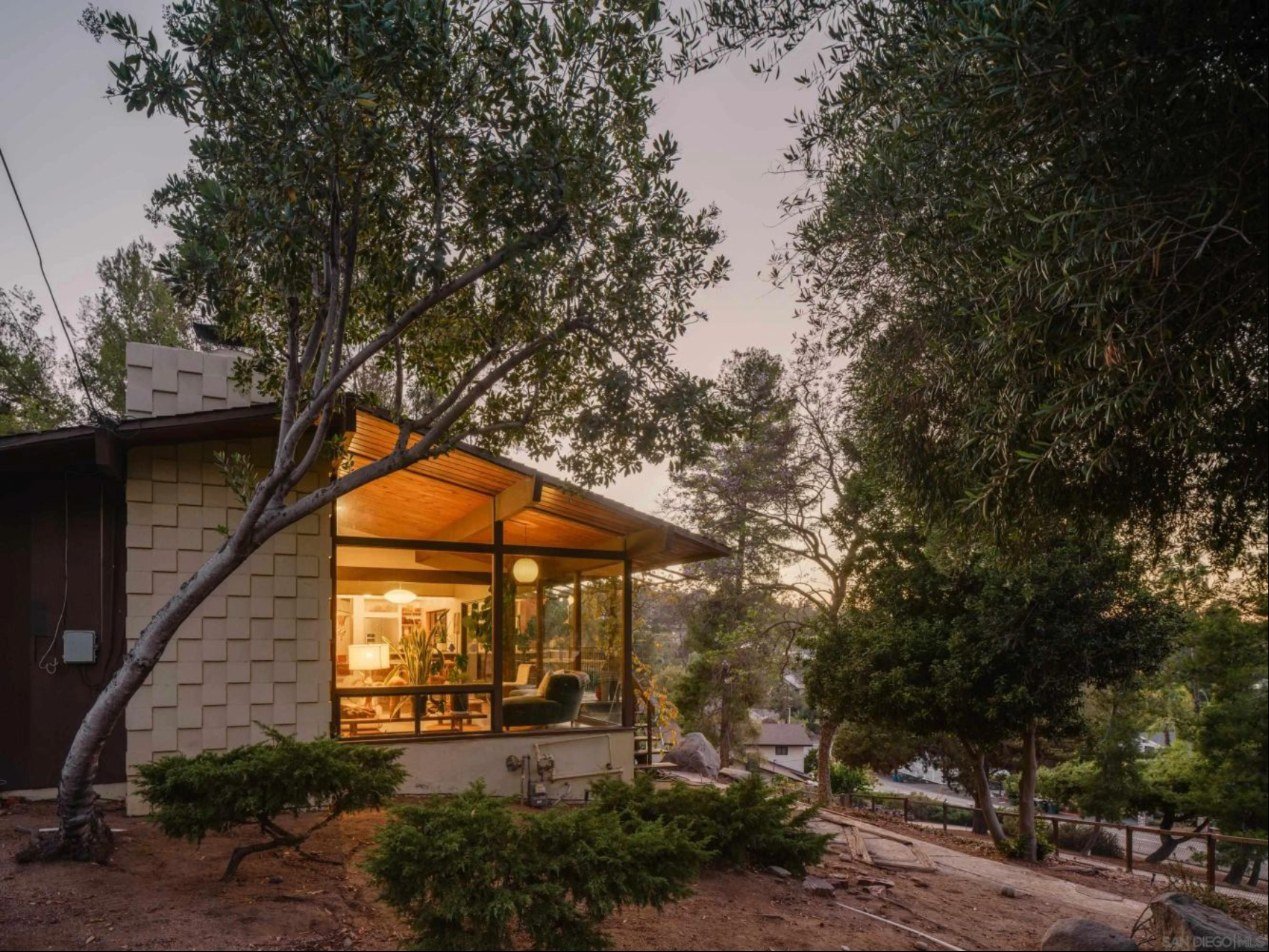
The Modernist Weekend: Four Architect-Designed Homes Worth the Drive

October 17, 2026
What the FAIR Plan covers, what it leaves out, and how a DIC policy fills the gap

October 9, 2026
Real listings, price per square foot by neighborhood, and the tradeoffs buyers face this fall

October 9, 2026
What San Diego's airport soundproofing program covers, who qualifies, and what buyers and sellers should know

October 9, 2026
A local guide to Loma Portal, La Playa, Fleetridge, Sunset Cliffs and more, and who each one suits
October 4, 2026
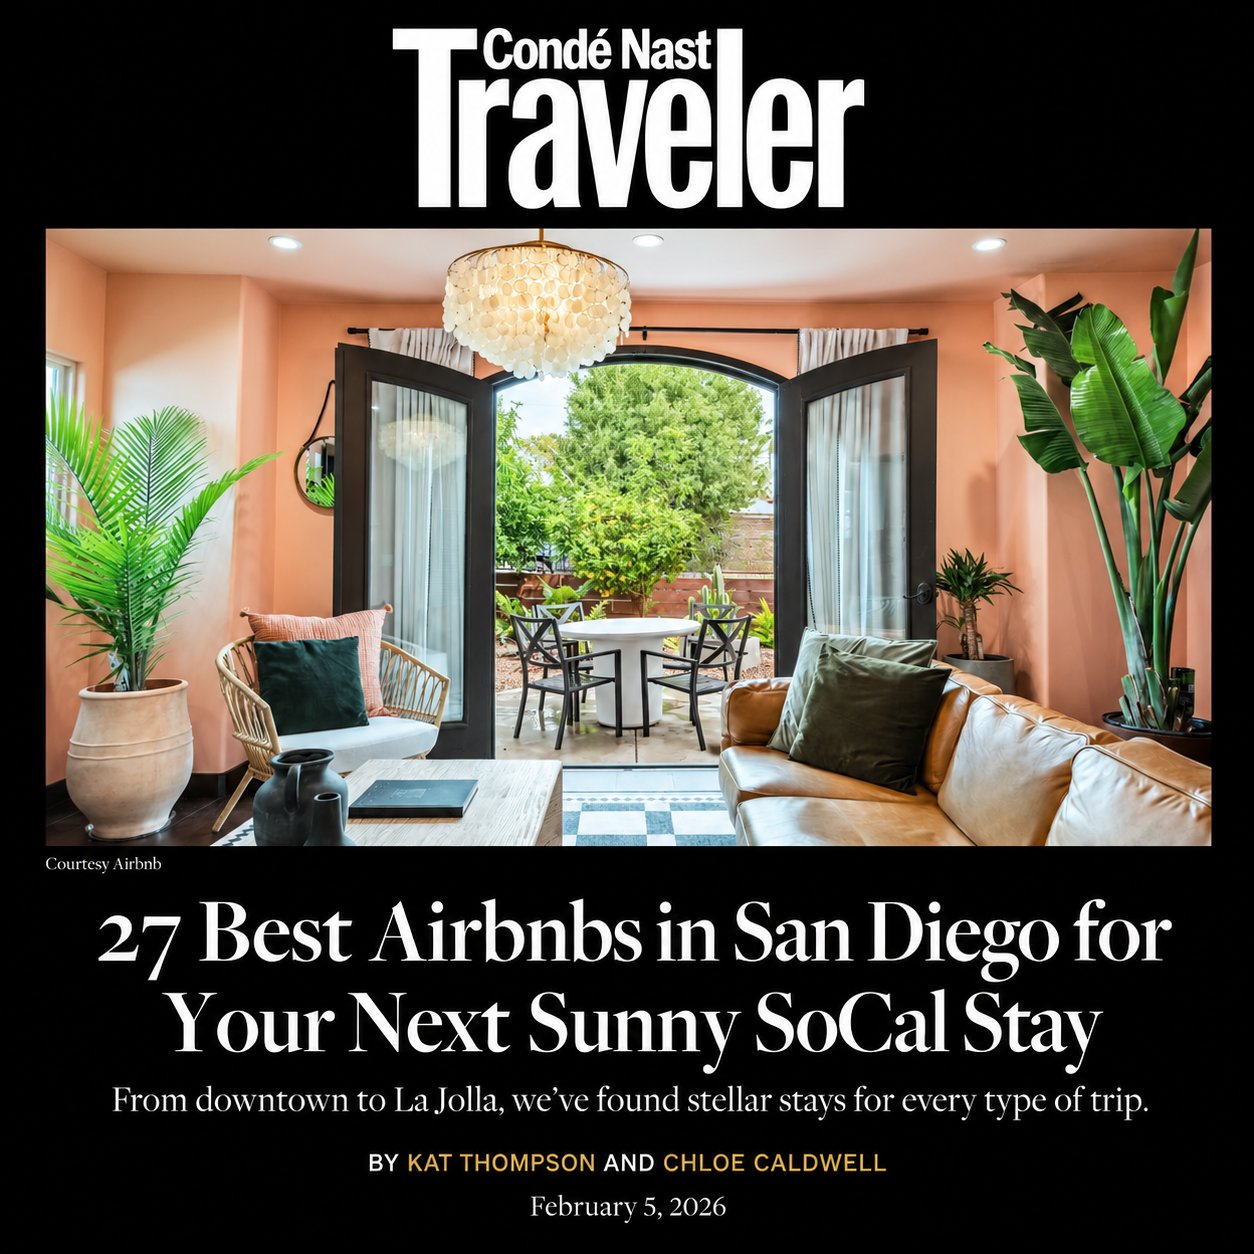
Our Mountain View retreat is featured in Condé Nast Traveler's guide to San Diego's best Airbnbs for the fourth year in a row

October 3, 2026
Neighborhoods, nightlife and what to expect, from a gay realtor who lives here

October 3, 2026
How a 2% seller credit can lower your monthly payment more than a price cut

October 3, 2026
How STR owners use cost segregation and 100% bonus depreciation to write off more in year one
Get assistance in determining current property value, crafting a competitive offer, writing and negotiating a contract, and much more. Contact Josh today.