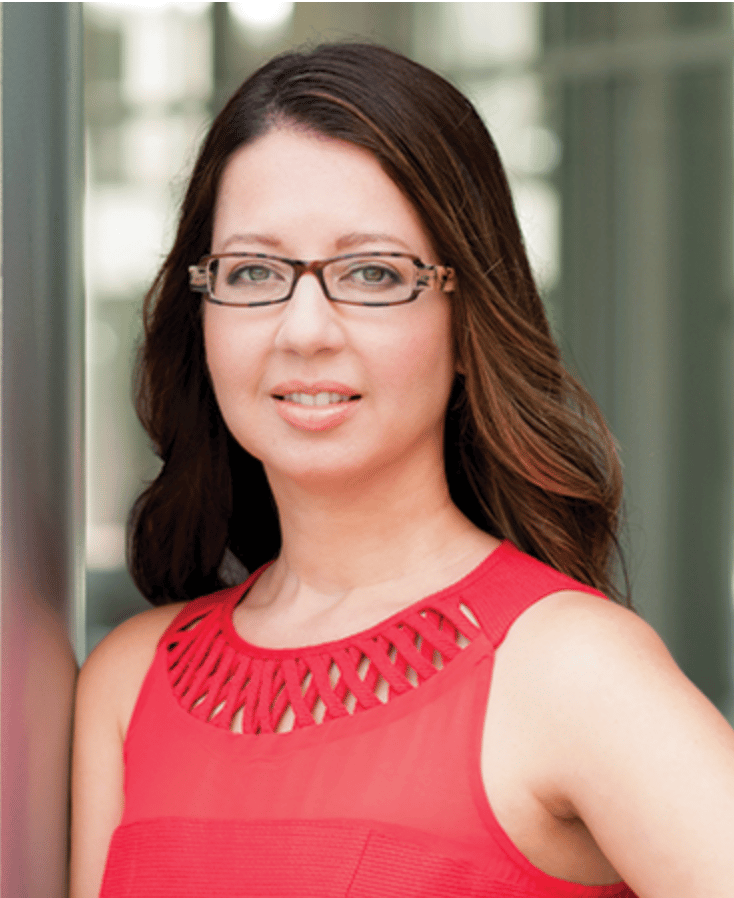
Q & A with lender Felisa about Debt Consolidation
ADVICE September 15, 2026
ADVICE September 15, 2026
If you bought or refinanced a home in 2020 or 2021, there’s a good chance you’re holding onto a mortgage rate you have no interest in giving up. But while your mortgage may be sitting comfortably around 3%, credit cards and other consumer debt can be charging 20% or more.
That’s where debt consolidation can become worth exploring.
Many homeowners have built significant equity over the past several years, and accessing that equity doesn’t necessarily mean refinancing your existing mortgage. Options such as a HELOC or home equity loan may allow you to keep your current first mortgage in place while using some of your equity to tackle higher-interest debt.
I sat down with lender Felisa Schlosser to break down what debt consolidation actually is, how homeowners can use their equity, what it could look like in real numbers and, just as importantly, when it may not be the right move.
Here’s what homeowners should know.
What exactly is debt consolidation? At its core, debt consolidation means combining multiple debts — credit cards, personal loans, whatever's out there — into a single payment, usually at a lower interest rate. Instead of juggling five different bills with five different due dates and interest rates, you're paying one. For homeowners, one of the most effective ways to do this is by using the equity in your home, since home equity rates are typically far lower than credit card rates.
If someone has a low mortgage rate from 2020 or 2021, can they access their equity without refinancing and losing that rate? Yes, and this is honestly the question I get most often right now. A lot of people assume that tapping into their equity means refinancing their whole mortgage — and touching that 3% rate feels like a nonstarter. But a second mortgage, like a HELOC or a home equity loan, lets you borrow against your equity while leaving your first mortgage completely untouched. Your original rate stays exactly where it is.
If someone has $40,000 in credit card debt at 20% to 25% interest, what could debt consolidation potentially look like for them? That's a great example of where this really moves the needle. At 20-25% interest, a big chunk of every payment is just going to interest, not the balance. Move that $40,000 to a home equity loan or HELOC, and depending on the rate, you could be looking at a fraction of that interest cost — which means more of your payment actually pays down debt, and your monthly payment itself is often lower too. The exact numbers depend on your equity, credit, and the loan structure, but the potential savings are usually significant.
How can homeowners use the equity in their home to consolidate debt? Your home equity is essentially the value you've built up — the difference between what your home is worth and what you still owe. A second mortgage lets you borrow against that value, either as a lump sum (home equity loan) or a flexible line of credit (HELOC), and use it to pay off higher-interest debt. It turns equity you already have into a tool that works for you.
Are there situations where you would recommend that someone not consolidate their debt? Absolutely, and I think it's important to say that out loud. Debt consolidation isn't a fit for everyone. If the underlying spending habits that created the debt haven't changed, consolidating can sometimes just free up credit to accumulate more debt down the road. And if someone doesn't have enough equity, or the new payment doesn't actually improve their situation, it's not the right move. This is exactly why I always recommend running the numbers with someone before deciding — it should make your situation better, full stop.
If someone is wondering whether debt consolidation could benefit them, what should their first step be? Just reach out and have a conversation. There's no cost and no obligation to run your numbers — I'll look at your current debt, your rate, your equity, and tell you honestly whether it makes sense. Sometimes it does, sometimes it doesn't, but you'll walk away knowing which one it is.
Stay up to date on the latest trends in real estate.
November 3, 2026
How The Carmine Collection manages a few select San Diego homes, what it costs, and the STRO rules every owner should know

November 3, 2026
How living upstairs and renting the lock-off downstairs under a home sharing license covered my mortgage

November 3, 2026
The research report, the criteria, the hearing, and what changes after.
November 2, 2026
What running The Carmine Collection taught me about selling homes.

October 28, 2026
Where to live near each San Diego base and major employer, and how a VA loan turns BAH into equity

October 28, 2026
How bonus depreciation, Tier 3 licenses and motivated sellers line up before December 31
October 17, 2026
The Modernist Weekend: Four Architect-Designed Homes Worth the Drive

October 17, 2026
What the FAIR Plan covers, what it leaves out, and how a DIC policy fills the gap

October 9, 2026
Real listings, price per square foot by neighborhood, and the tradeoffs buyers face this fall
Get assistance in determining current property value, crafting a competitive offer, writing and negotiating a contract, and much more. Contact Josh today.