
How San Diego Buyers Can Beat High Interest Rates with Seller Credits
ADVICE Josh Taylor. October 3, 2026
ADVICE Josh Taylor. October 3, 2026
Rates are up. The average 30-year jumbo rate is sitting around 7.5% in early October 2026 (U.S. News). That keeps a lot of buyers on the sidelines, and fewer buyers means sellers are more open to negotiating.
Most buyers only negotiate on price. Smart buyers negotiate on payment. A seller credit aimed at your interest rate can save you three times more each month than a price cut of the same size.
Instead of only asking for a lower price, ask the seller to put about 2% of the purchase price toward your loan costs. On a $1.5M home, that is $30,000.
Sellers often prefer this. Their sale price stays strong for the comps, and their net is about the same as a price cut.
A temporary buydown lowers your rate for the first one to three years, then steps up to your full rate. The seller's credit is held in an account that tops up your payment each month.
Think of it like a gym intro offer: cheaper at the start, full price later, and you know exactly when it ends.
Most lenders still qualify you at the full rate, so a buydown helps cash flow, not buying power.
On a $1.5M purchase, a 2-1 buydown uses almost exactly a 2% credit and saves about $1,578 a month in year one.
Assumptions: 20% down ($300,000), a $1.2M loan at 7.5% on a 30-year fixed, and a $30,000 seller credit. Payments are principal and interest only.
Option | Year 1 rate | Year 1 payment | Cost to fund |
|---|---|---|---|
No buydown | 7.5% | $8,391 | $0 |
1-1 buydown | 6.5% | $7,585 | about $19,300 |
2-1 buydown | 5.5% | $6,813 | about $28,600 |
3-2-1 buydown | 4.5% | $6,080 | about $56,300 |
The 1-1 leaves about $10,700 of the credit for closing costs. The 3-2-1 needs closer to a 4% credit on a loan this size.
If rates fall in the next couple of years, you refinance. Any unused buydown funds usually go toward your loan balance.
A temporary buydown is a discount that expires. Buying points lowers your rate for the life of the loan.
One point costs 1% of your loan amount, not the purchase price. On a $1.2M loan, that is $12,000. Each point usually drops your rate about 0.25%, though it can range from 0.125% to 0.375% depending on the lender and that day's pricing.
Your down payment matters because it sets the loan size. Put more down and every point gets cheaper.
Here is the same $30,000 used three ways:
Use of the $30K | Monthly savings | How long it lasts |
|---|---|---|
Price cut | about $168 | Life of the loan |
2-1 buydown | $1,578 in year 1, $806 in year 2 | 2 years |
2.5 points (7.5% to about 6.875%) | about $508 | Life of the loan |
Points break even in about five years. After that, every month is pure savings.
Every lender prices this differently, especially on jumbo loans, so run your numbers with a lender before you write the offer. Figures above are estimates for illustration, not a loan quote.
Buying in San Diego and want to structure an offer like this? Call or text Josh Taylor at Compass on 760.704.3820, email [email protected], or visit aussiejosh.com.
Stay up to date on the latest trends in real estate.
October 17, 2026
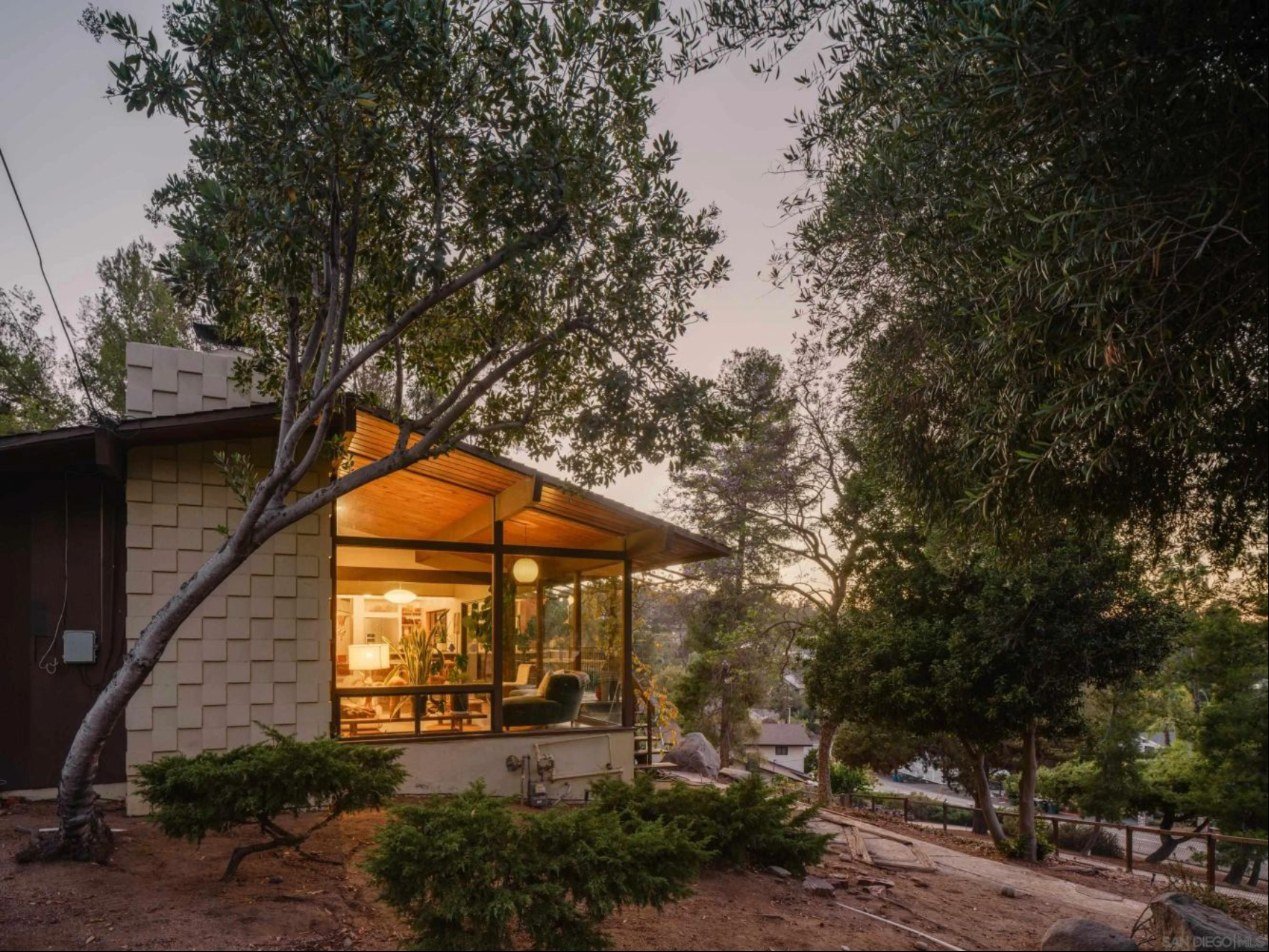
The Modernist Weekend: Four Architect-Designed Homes Worth the Drive

October 17, 2026
What the FAIR Plan covers, what it leaves out, and how a DIC policy fills the gap

October 9, 2026
Real listings, price per square foot by neighborhood, and the tradeoffs buyers face this fall

October 9, 2026
What San Diego's airport soundproofing program covers, who qualifies, and what buyers and sellers should know

October 9, 2026
A local guide to Loma Portal, La Playa, Fleetridge, Sunset Cliffs and more, and who each one suits
October 4, 2026
Our Mountain View retreat is featured in Condé Nast Traveler's guide to San Diego's best Airbnbs for the fourth year in a row

October 3, 2026
Neighborhoods, nightlife and what to expect, from a gay realtor who lives here
October 3, 2026
How a 2% seller credit can lower your monthly payment more than a price cut

October 3, 2026
How STR owners use cost segregation and 100% bonus depreciation to write off more in year one
Get assistance in determining current property value, crafting a competitive offer, writing and negotiating a contract, and much more. Contact Josh today.