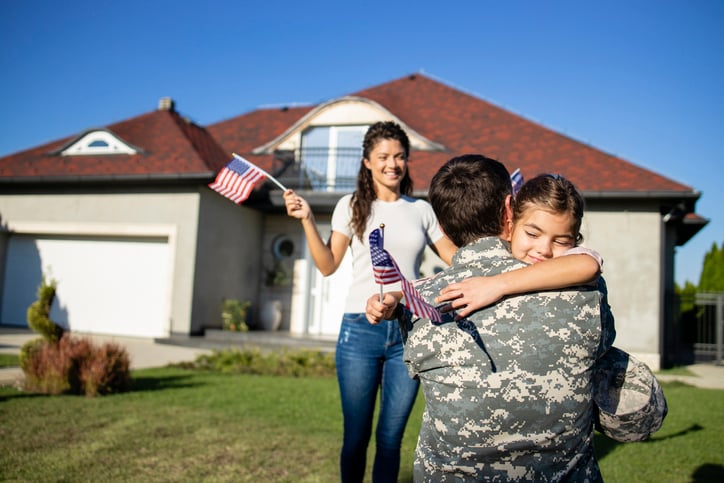
Why Some Homes and Condos Qualify for VA Loans — and Others Don’t
Josh Taylor. October 25, 2025
Josh Taylor. October 25, 2025
For veterans and active-duty service members, VA loans are one of the most powerful tools for achieving homeownership. With zero down payment, no private mortgage insurance (PMI), and competitive interest rates, the VA loan program helps make buying a home far more attainable.
But if you’ve ever searched for a home using your VA benefits, you might have noticed that some properties are eligible and others aren’t. Understanding why can help you save time and make smarter decisions when buying.
When people say a home is “VA approved,” they usually mean that the property meets the VA’s Minimum Property Requirements (MPRs) — a set of safety, structural, and livability standards designed to ensure the home is move-in ready and a sound investment.
The VA doesn’t pre-approve homes in advance. Instead, each property is evaluated by a VA-certified appraiser during the loan process. The appraiser’s job is to make sure the property is safe, structurally solid, and sanitary, following the MPR checklist.
The MPRs exist to protect both the veteran and the lender. They help confirm that the home you’re buying is in good condition and won’t require significant repairs right away. Here are the main categories the VA looks at:
Safety: The home must be free from hazards such as exposed wiring, broken windows, or unstable decks.
Soundness: The structure must be solid, including the roof, foundation, and walls.
Sanitation: Plumbing, water, and sewage systems must work properly and meet health standards.
Access: The property must have safe year-round access via public or private roads.
Utilities: Water, electricity, and heating systems must all function properly.
Homes that need major repairs or have safety issues may not qualify until those items are fixed.
Even great-looking homes can fall short of VA standards. Common disqualifiers include:
Fixer-Uppers: Homes requiring extensive repair or renovation may not meet VA guidelines.
Unpermitted Work: Additions, garage conversions, or ADUs without proper permits can prevent approval.
Non-Traditional Properties: Mixed-use buildings or homes with commercial elements often don’t qualify.
Condos are particularly tricky under VA rules. The VA maintains a Condominium Approval List — a database of complexes that meet its financial and structural standards. If a condo isn’t on that list, buyers can’t use VA financing there without additional steps.
Here’s why some condos don’t make the cut:
The VA reviews the financial stability of the homeowners association (HOA). If the HOA doesn’t maintain strong reserve funds for future maintenance, it signals risk. Without healthy reserves, the HOA may need to issue special assessments — one-time fees charged to homeowners to cover unexpected repairs, like replacing a roof or plumbing system.
These assessments create financial uncertainty for owners and lenders, which can lead the VA to deny approval for that condo community.
If too many units in the complex are rented out rather than owner-occupied, the VA may see the community as unstable. Owner-occupied properties tend to be better maintained and more financially reliable, which is key for loan approval.
Active litigation involving the HOA or the building’s developer — such as disputes over construction defects — can make the property ineligible until the matter is resolved.
VA approval for condos is not permanent. Complexes must resubmit their documents periodically to stay on the VA-approved list. Some HOAs let their approval lapse because they don’t see immediate demand from VA buyers, or they fail to complete the required renewal paperwork. Once the approval expires, the complex is no longer eligible for VA financing until it’s re-approved.
If a buyer or HOA wants to make a complex eligible again, the HOA board (or management company) can submit an application directly to the U.S. Department of Veterans Affairs. The process involves submitting financial statements, bylaws, insurance documents, and other records for review.
While the process can take time, some lenders specialize in helping condo associations through re-approval. If a property you love isn’t currently approved, it’s worth asking your lender or real estate agent if it can be added back to the list.
You can check the current VA condo approval list here: VA Condo Lookup Tool.
Work with a VA-Savvy Agent: Choose a real estate agent experienced in VA transactions who knows how to identify eligible properties early.
Get Pre-Approved Before Shopping: A VA lender can help flag potential issues before you submit an offer.
Ask Questions About the HOA: For condos, request the latest financials and meeting minutes to gauge stability.
Don’t Be Discouraged: Even if a home or condo isn’t currently VA approved, sometimes the issues can be resolved — especially if the seller is motivated or the HOA is willing to cooperate.
Not every home or condo is VA approved, but that doesn’t mean your dream home is out of reach. By understanding what the VA looks for, you can focus your search on properties that qualify, avoid delays, and take full advantage of the incredible benefits your VA loan offers.
Stay up to date on the latest trends in real estate.
November 3, 2026
How The Carmine Collection manages a few select San Diego homes, what it costs, and the STRO rules every owner should know

November 3, 2026
How living upstairs and renting the lock-off downstairs under a home sharing license covered my mortgage

November 3, 2026
The research report, the criteria, the hearing, and what changes after.
November 2, 2026
What running The Carmine Collection taught me about selling homes.

October 28, 2026
Where to live near each San Diego base and major employer, and how a VA loan turns BAH into equity

October 28, 2026
How bonus depreciation, Tier 3 licenses and motivated sellers line up before December 31
October 17, 2026
The Modernist Weekend: Four Architect-Designed Homes Worth the Drive

October 17, 2026
What the FAIR Plan covers, what it leaves out, and how a DIC policy fills the gap

October 9, 2026
Real listings, price per square foot by neighborhood, and the tradeoffs buyers face this fall
Get assistance in determining current property value, crafting a competitive offer, writing and negotiating a contract, and much more. Contact Josh today.